The 2026 Year-End Guide outlines the proactive steps Applicable Large Employer (ALE) clients can take now to ensure a smooth ACA year end and accurate 1095-B and 1095-C forms.
Action required: Communicate any ACA changes to the HRCore ACA team at HRCoreACA@insperity.com by Dec. 1, 2026. Before you send your changes, confirm that your ACA configuration, employee statuses and benefit elections are complete and accurate.
Key dates: Your ACA forms will be ready for approval on Jan. 1,2027, and must be reviewed and approved by Jan. 22, 2027. By Nov.30, 2026, all companies that have chosen to implement ACA will receive communication with the steps to review and approve their forms. You can find more information and steps to review and approve your ACA forms in2026 Year-End Guide.
If you do not receive this notification, contact the HRCore ACA team at HRCoreACA@insperity.com.
The General Services Administration issued its annual updated list of federal maximum per diem rates for travel to locations within the continental United States (CONUS). The new rates are effective for travel undertaken on or after October 1, 2026.
The standard CONUS meal and incidental expense (M&IE) rate will remain $68. The M&IE rates for non-standard areas (NSAs) also will not change and remain $68, $74, $80, $86 and $92.
For all locations within CONUS not shown on the list, the lodging per diem will increase to $113 (from $110), the M&IE rate will remain $68, and the combined maximum standard per diem rate will increase to $181 (from $178).
NSA locations
For fiscal year 2027, there are 295 NSAs. The combined per diem rates for the listed NSA locations range from a low of $181 (off-season) for several locations to a high of $591 (peak season) for Park City, Utah. Allentown, Pennsylvania, was an NSA in fiscal year 2026 and has been moved into the standard CONUS rate category.
Tax season is getting a little simpler for HRCore employees!
Through a new integration between isolved People Cloud™ and H&R Block, employees will be able to import their W-2 information directly from isolved into H&R Block when preparing their taxes. This eliminates the need to manually enter W-2 details, helping simplify tax preparation while reducing the potential for data-entry errors.
More convenience. More choice.
The new H&R Block integration gives employees another option for preparing their taxes. Similar to the existing TurboTax integration, employees who prefer H&R Block can securely import their W-2 information directly into their tax return. Even better, employees who take advantage of the isolved and H&R Block offer will receive a 20% discount on H&R Block tax filing. For HRCore clients, these integrations will be made available at no additional cost.
What this means for your employees
When it is time to file, employees who choose H&R Block can:
Save time by importing W-2 information directly from isolved rather than entering it manually.
Reduce manual entry of W-2 information during tax preparation.
Choose the tax-preparation option that works best for them, with both H&R Block and TurboTax integrations available through isolved.
Save 20% on H&R Block tax filing when using the isolved offer.
It is another way HRCore and isolved are working to make everyday experiences easier for employees by connecting tools they already use with the information they need. Look for the H&R Block option when W-2s become available online for the upcoming tax season.
In isolved People Cloud™, employees can opt in for electronic delivery of year-end tax forms, including W-2s, 1099s and 1095s (if using isolved for ACA compliance). This feature offers a more secure method for employees to receive their tax forms. It also provides them with:
Earlier access to their tax forms compared to regular mail delivery
Automated alerts when the forms are ready
Convenience of retrieving their forms 24/7
Electronic delivery is an employee choice, so each employee must complete their own consent election.
Reminders to employees who have not yet signed up for electronic delivery of W-2s can go a long way in ensuring they opt-in before the cutoff date for 2026, which is prior to the last payroll of the year.
Ready to help your employees skip the mailbox? Visit the Insperity HCM Knowledgebase for step-by-step guidance and resources to support electronic delivery.
In accordance with your agreement and Form 8655 (Reporting Agent Authorization), this notification serves as confirmation that your third-quarter 2026 payroll tax returns and payments have been filed on your behalf by Insperity® Payroll Services.
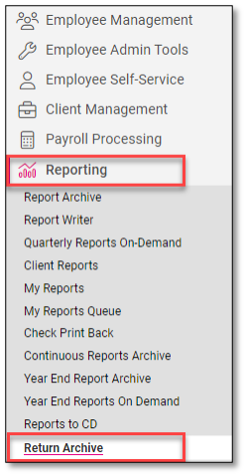
Third-quarter report packages will be available in isolved on Nov. 3 and include all tax returns that were filed by Insperity. To access your quarterly report packages, log in to isolved and navigate to Return Archive under the Reporting menu.
You can filter the list of available report packages by using the drop-down menus at the top of the screen, shown below.
Ongoing tax communication
As a reminder, you should send all payroll-related tax communications you receive to your Insperity payroll specialist for review. Insperity does not receive direct communication regarding your tax accounts from state and federal agencies, and these notices may contain important pieces of tax information needed for correct and timely tax payments and filings. Incorrect or missing information may result in penalties and interest assessed by the tax agency. Insperity is not responsible for any penalties and interest charged.
✅ Notification of any plan, eligibility or contribution changes
Open Enrollment timeline
70 days before your benefit renewal date
Your assigned Open Enrollment Specialist will contact you to introduce the process, discuss key dates and request the information needed to prepare your Open Enrollment event.
At least 14 days before your desired Open Enrollment start date
Clients should submit all renewal documentation, benefit rates, contribution details, enrollment dates and employee communication materials. This allows adequate time for configuration, rate validation, Open Enrollment Wizard setup and client review.
Prior to Open Enrollment launch
Your Open Enrollment Specialist will complete system configuration and provide the enrollment setup for your review and approval.
Open Enrollment begins
Employees receive access to enroll and make benefit elections during the scheduled enrollment period.
After Open Enrollment closes
Final elections are processed and prepared for the upcoming plan year.
Submitting renewal information as early as possible helps ensure sufficient time for setup, review and employee communication prior to your Open Enrollment launch.
With Q4 underway and year-end payroll processing approaching, it’s important to understand how the SECURE 2.0 catch-up requirements will affect 401(k) contributions for Highly Paid Individuals (HPIs) in 2026.
The SECURE 2.0 law mandates that an employee who earned more than $150,000 in taxable social security wages in 2025 is considered a Highly Paid Individual (HPI) and must make all catch-up contributions as Roth. By the end of the year, HPIs may contribute a maximum of $24,500 as pre-tax contributions up to the standard limit, with the remainder as Roth contributions up to their catch-up limit.
401(k) contribution limits by age and HPI status
Category
2026 Base Limit
Maximum Possible Total Contribution (HPI or not HPI)
Maximum Possible Pre-tax Contribution If not HPI
Maximum Possible Pre-tax Contribution HPI
Deferral (Under age 50)
$24,500
$24,500
$24,500
$24,500
Catch-Up (Age 50 – 59 or 64+)
$8,000
$32,500
$32,500
$24,500
Optional Super Catch-Up (Age 60 – 63)
$11,250
$35,750
$35,750
$24,500
How this requirement is handled in payroll
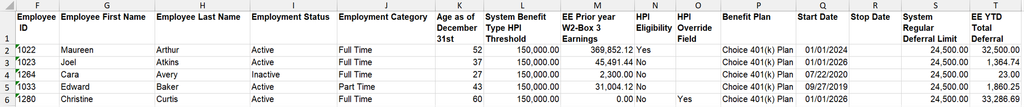
Insperity HRCore uses isolved functionality to automatically support the SECURE 2.0 Roth catch-up requirement. When 2025 W-2s are available in isolved, employees with more than $150,000 in prior-year Social Security taxable wages are automatically identified as highly paid individuals for 2026. Clients can also mark employees as HPIs using the Highly-paid Individual Override option on their Deferred Comp benefit record if they were not automatically identified.
When payroll is processed, the system automatically moves all catch-up retirement contributions to the 401(k) Roth HPI deduction for employees who are flagged as HPIs. This feature assumes all previous contributions up to the standard $24,500 limit were made as Pre-tax, so all remaining contributions should be Roth.
In practice, highly paid individuals may have elected both Roth and Pre-tax contributions throughout the year. If an HPI employee has already made Roth contributions before they reach the standard $24,500 limit, the automated functionality prevents them from maximizing pre-tax contributions.
Your Insperity Payroll service team can assist with workarounds to accommodate HPIs who need to attribute Roth contributions they made throughout the year as Roth catch-up so they can maximize their Pre-tax contributions.
Follow these steps to verify your retirement configuration for SECURE 2.0 HPI compliance:
What you need to do
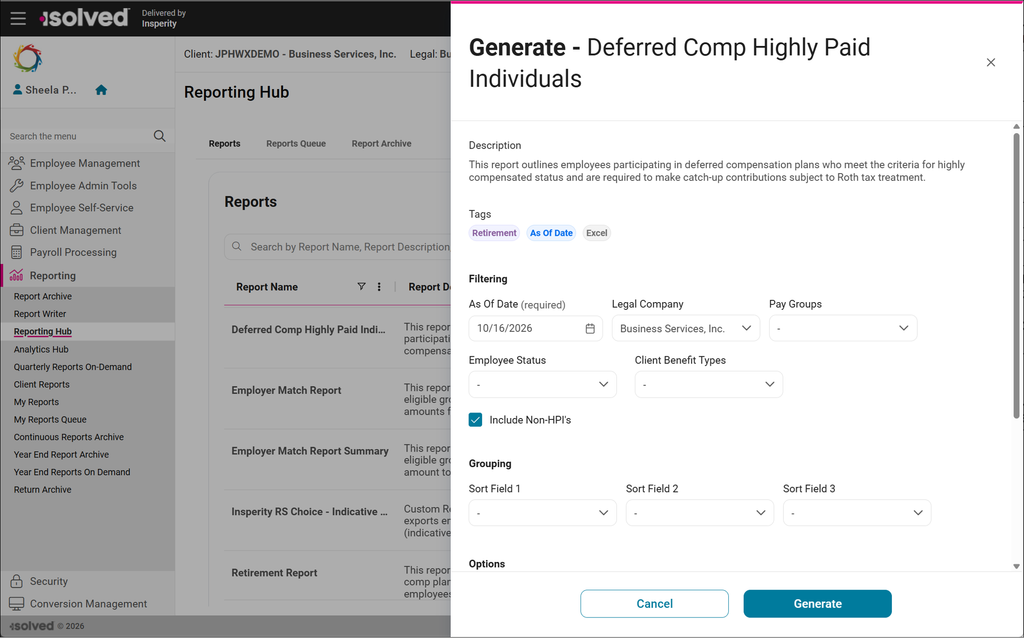
1. Run the Deferred Comp Highly Paid Individuals report in isolved to identify employees participating in deferred compensation plans who meet the criteria for HPI.
To run this report, go to the Reporting Hub and select All Reports. Search for Deferred Comp or Highly Paid to locate the report or filter your Tags to Retirement. If you don’t see the Deferred Comp Highly Paid Individuals report in your list, contact your Payroll Specialist to add it to your Standard Reports group. Check Include Non-HPI’s to list all employees.
2. Review the deferral rate elections for your HPI employees to identify anyone contributing to both pre-tax and Roth. Review employees who expect to maximize their pre-tax contributions and need to apply Roth contributions towards the catch-up requirement and limit.
Employee deferral rateelections can be found:
On the employee’s Deferred Comp benefit record
On the Retirement Report (Contr. values)
You can review year-to-date contribution amounts using:
Employee Pay History YTD Amounts
Retirement Report YTD Amounts
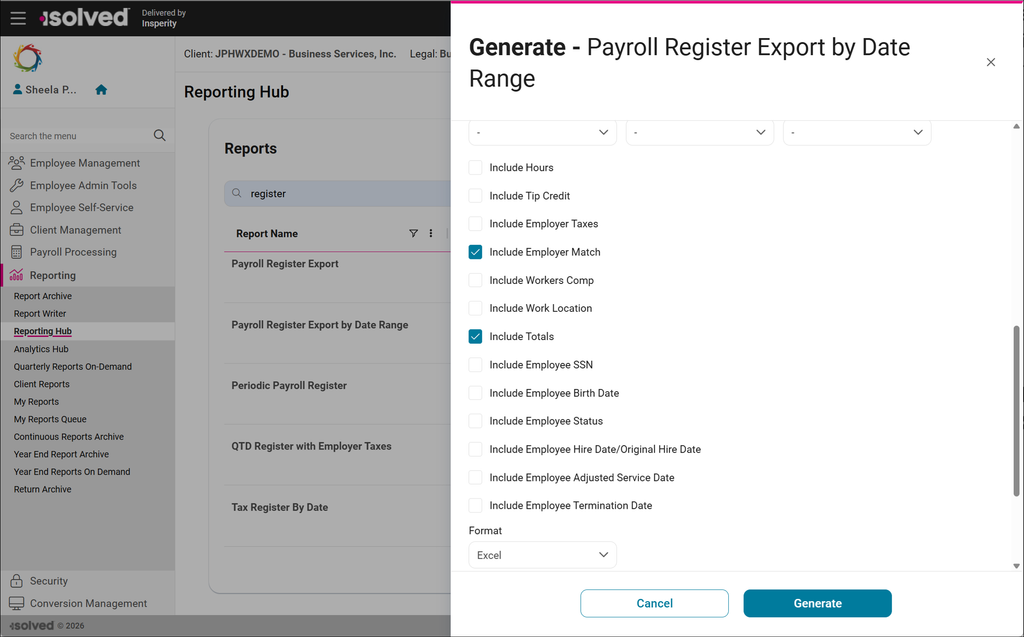
Payroll Register Export by Date Range with YTD deduction columns When running the Payroll Register Export by Date Range, be sure to select the Include Employer Match box at the bottom to include employer retirement contributions on the report.
3. Contact your Payroll Specialist if you identify an HPI who wants to continue making pre-tax contributions but is prevented from doing so because of the automated Roth treatment described above. Your Payroll Specialist can configure the necessary setup and walk you through the workaround to allow additional pre-tax contributions up to the standard contribution limit.
How to automatically maximize pre-tax contributions for 2027
To make this process easier next year, let your highly paid individuals know to elect Pre-tax contributions only in 2027. The system will automatically convert their contributions to Roth once they reach the 2027 IRS Section 402(g) standard limit to comply with the catch-up requirement.
✅ Notification of any plan, eligibility or contribution changes
Open Enrollment timeline
70 days before your benefit renewal date
Your assigned Open Enrollment Specialist will contact you to introduce the process, discuss key dates and request the information needed to prepare your Open Enrollment event.
At least 14 days before your desired Open Enrollment start date
Clients should submit all renewal documentation, benefit rates, contribution details, enrollment dates and employee communication materials. This allows adequate time for configuration, rate validation, Open Enrollment Wizard setup and client review.
Prior to Open Enrollment launch
Your Open Enrollment Specialist will complete system configuration and provide the enrollment setup for your review and approval.
Open Enrollment begins
Employees receive access to enroll and make benefit elections during the scheduled enrollment period.
After Open Enrollment closes
Final elections are processed and prepared for the upcoming plan year.
Submitting renewal information as early as possible helps ensure sufficient time for setup, review and employee communication prior to your Open Enrollment launch.
The IRS has announced a midyear increase to the standard mileage rate due to rising fuel costs. Effective July 1 through December 31, 2026, the business mileage reimbursement rate increased from 72.5 cents to 76 cents per mile. This rate determines the amount employers can reimburse employees for business travel on a tax-free basis.
The IRS also raised the mileage rate for medical travel and eligible moving expenses for active-duty military personnel and certain intelligence community members. These rates increased from 20.5 cents to 23.5 cents per mile beginning July 1, 2026.
The charitable mileage rate remains unchanged at 14 cents per mile, as it is set by federal statute and cannot be adjusted administratively by the IRS.
These rate increases come in response to volatile fuel prices, which have risen significantly in recent months. Higher gas prices have created additional financial pressure for employees, prompting the IRS to make the unusual mid-year adjustment to better reflect current driving costs.
As year-end approaches, now is a great time to encourage your employees to review and use any remaining paid time off (PTO) and flexible spending account (FSA) funds. A simple reminder can help employees make the most of their benefits, plan for time away and avoid forfeiting eligible FSA dollars.